
Does Earnings Beat Change The Bull Case For Halliburton Stock (HAL)?
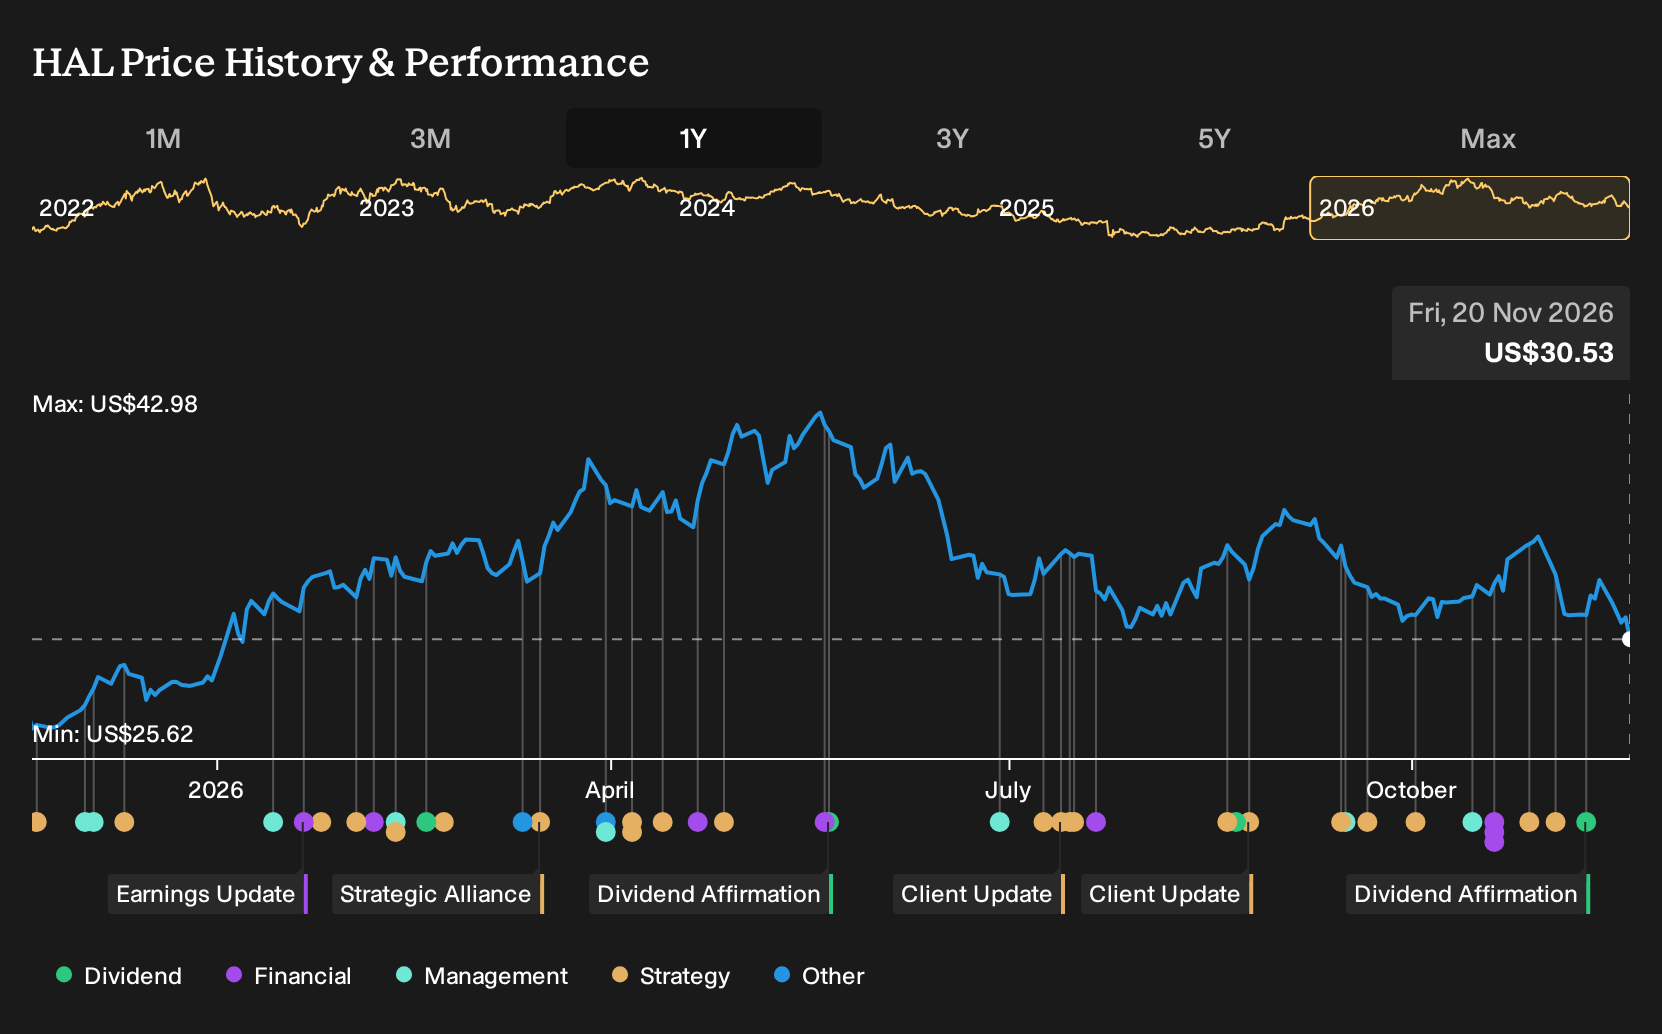
- Halliburton reported Q3 2026 adjusted earnings of $0.60 per share that were above estimates, with revenue supported by stronger drilling activity and international operations, while North American stimulation activity and the Completion and Production segment faced pressure.
- The board also affirmed a 2026 fourth quarter dividend of $0.17 per share. This, together with solid Drilling and Evaluation performance, highlights how Halliburton is leaning on international work and cash returns even as parts of its North American business soften.
- We will now look at how Halliburton's earnings beat from stronger international operations could reshape the investment narrative around its cash generation.
Compare how Halliburton's international tilt and dividend focus stack up against other potential opportunities by scanning our hand picked 41 high quality undervalued stocks that share strong fundamentals and pricing support.
Halliburton Investment Narrative Recap
To own Halliburton, you need to believe the international engine and technology heavy contracts described in the analyst consensus narrative on Simply Wall St continue to support activity even as parts of North America remain softer. The latest earnings beat fits that view, with Drilling and Evaluation strength offsetting weaker Completion and Production and giving management room to prioritize margin discipline.
The closest short term swing factor is how quickly international awards translate into consistent cash generation while North American stimulation remains under pressure. The biggest near term risk is that conflict related disruptions or logistics costs in key regions dilute that overseas margin story. The recent news does not materially change those core drivers.
The fourth quarter 2026 dividend of US$0.17 per share is the clearest fresh signal to consider in this context. It indicates that Halliburton is still committing cash to shareholders while relying on international contracts and technology driven work to support the payout, despite softer domestic activity and a share price that has fallen about 13.6% over 90 days.
For you, the dividend affirmation links directly to the catalysts and risks. Disciplined capital allocation and higher international utilization need to support both that cash return and Halliburton’s higher debt load and more volatile dividend track record. If activity in sensitive regions slows or decarbonization pressure affects upstream budgets, the balance between sustaining that dividend and funding growth projects becomes more finely tuned.
Halliburton's current earnings are about US$1.6b, with analyst consensus pointing to earnings of US$2.7b by 2029. This implies an increase of roughly US$1.1b, alongside forecast annual revenue growth of 3.9% that would see total sales reach about US$25.1b in that same year.
Discover why Halliburton's fair value indicates a 42% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Halliburton’s free cash flow potential rather than dividend steadiness. Before this dividend news, the bullish narrative explored revenue of about US$26.9b and earnings near US$3.3b by 2029. That is far more upbeat than consensus, and this earnings beat plus dividend affirmation could push those narratives to evolve.
Explore 4 other Halliburton fair value estimates, including one that suggests as much as 125% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Halliburton research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Halliburton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halliburton's overall financial health at a glance.
Looking for more investment ideas beyond Halliburton?
If you want to balance your view on Halliburton with a wider watchlist, the Simply Wall St Screener can help you quickly surface other companies that fit your style, whether you care most about value, resilience, or future potential.
- For investors trying to pair value with quality, you could start with a curated set of fundamentally strong opportunities by reviewing our 41 high quality undervalued stocks.
- If capital protection and steadier business profiles matter most to you, you might focus on companies with stronger balance sheets and lower risk profiles using the list of solid balance sheet and fundamentals (24 results).
- To look for potential future winners that are not yet widely followed, you can scan our 18 high quality undiscovered gems and see which smaller companies still show robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com