
Paladin Energy (ASX:PDN) Shares Look Rich Relative To Current Earnings
Paladin Energy has seen its share price fall sharply over the past few years, even as the business reports production and revenue from its uranium operations. With the stock under pressure, the live question is whether today’s market price can be supported by the company’s earnings profile.
- The share price has fallen 43.5% over the past three years, which puts the focus squarely on what the current valuation is asking investors to assume about future profitability.
- Recent AGM commentary pointed to production within cost targets and positive gross profit from uranium sales, which can influence how durable margins and future earnings power look at the current price.
- There is a second opinion on Paladin Energy worth weighing. See what analysts think Paladin Energy's shares could be worth.
For investors, the debate is whether Paladin Energy’s current share price is appropriately aligned with what its earnings suggest the business is worth.
To pressure test Paladin Energy’s recent share price slide against other ways of playing uranium and related materials, start with a focused screen of 16 nuclear energy infrastructure stocks.
Is Paladin Energy Getting Expensive on Earnings?
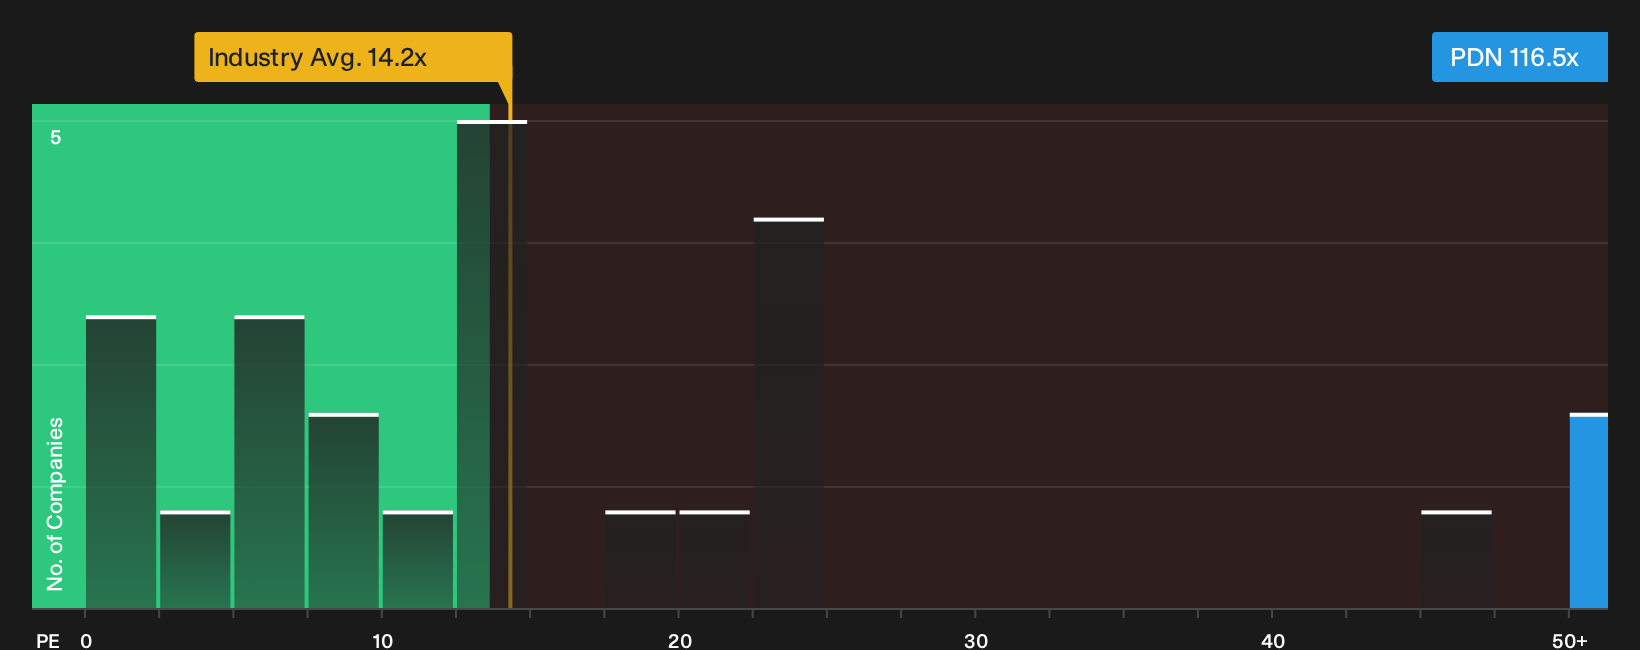
The P/E ratio is a useful lens for Paladin Energy because profit has become a more central part of the story after production and sales ramped up. On this measure, the stock trades on roughly 116.5x earnings, which is far richer than the broader Oil and Gas group on about 14.2x and also well above uranium and energy peers closer to 20.3x.
Modelled fair value for Paladin Energy suggests a lower multiple would better reflect its current mix of earnings quality, risk profile and reinvestment needs, and the gap is large enough that the model should be read as a warning signal rather than a precise target. Despite the strong 2026 AGM update on production and gross profit, the present P/E implies investors are paying a very full price for each dollar of reported earnings relative to sector benchmarks and to what the tailored model indicates. Explore the numbers behind Paladin Energy's P/E valuation.
The Paladin Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Paladin Energy pick up where the P/E puzzle leaves off. They set out the specific growth, margin and earnings paths that would need to play out for Paladin Energy’s current valuation to look conservative or stretched. Where a single ratio or model offers one number, these storylines explain the future that number relies on so you can watch in real time whether reality is tracking those expectations on the Community page.
Bulls and bears looking at Paladin Energy are reading the same uranium story but drawing very different conclusions about what the current price implies.
Bull case: 69% undervalued
According to tommyt, an investor in the Simply Wall St Community, the appeal starts with what Paladin Energy already has in hand.
"Paladin already has 22.3 million pounds contracted out to 2030 across 12 offtake agreements, with recent sales realised at US$69.90/lb..."
Discover why this Narrative puts Paladin Energy at 69% undervalued.
Bear case: 213% overvalued
Dhruva, a Simply Wall St Community investor who wrote the opposing Narrative, focuses on what could go wrong if the cycle turns.
"If uranium prices fall, margins can quickly shrink..."
Explore why this Narrative puts Paladin Energy at 213% overvalued.
One more Paladin Energy check that belongs beside the valuation work
Price ratios and narrative debates only tell part of the story, because Paladin Energy also trips specific risk checks that could change how you weigh everything else you have just read. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com