
MercadoLibre (MELI) Stock Looks About Right After A 31% Fall
MercadoLibre has seen its share price come under pressure this year, which naturally shifts attention to whether the current valuation is still supported by the earnings the business is generating. With the stock moving sharply over 2026, the live question is how that price now lines up against what the company earns for shareholders.
- The stock is down 31.3% year to date, which puts fresh focus on whether the earnings multiple investors are paying still makes sense.
- The group relies heavily on scaling its e-commerce and fintech operations to convert revenue into profit, so the pace and efficiency of that earnings conversion can reshape what an appropriate P/E range looks like.
- Your read on MercadoLibre is one view; the desks covering it have another. See what analysts think MercadoLibre's shares could be worth.
The stock's next move may depend on whether MercadoLibre's current share price is justified by the earnings that underpin it.
This same question about paying up for earnings applies well beyond MercadoLibre, so it can help to compare its slump with a set of 40 high quality undervalued stocks.
Does MercadoLibre Look Fairly Valued on Earnings?
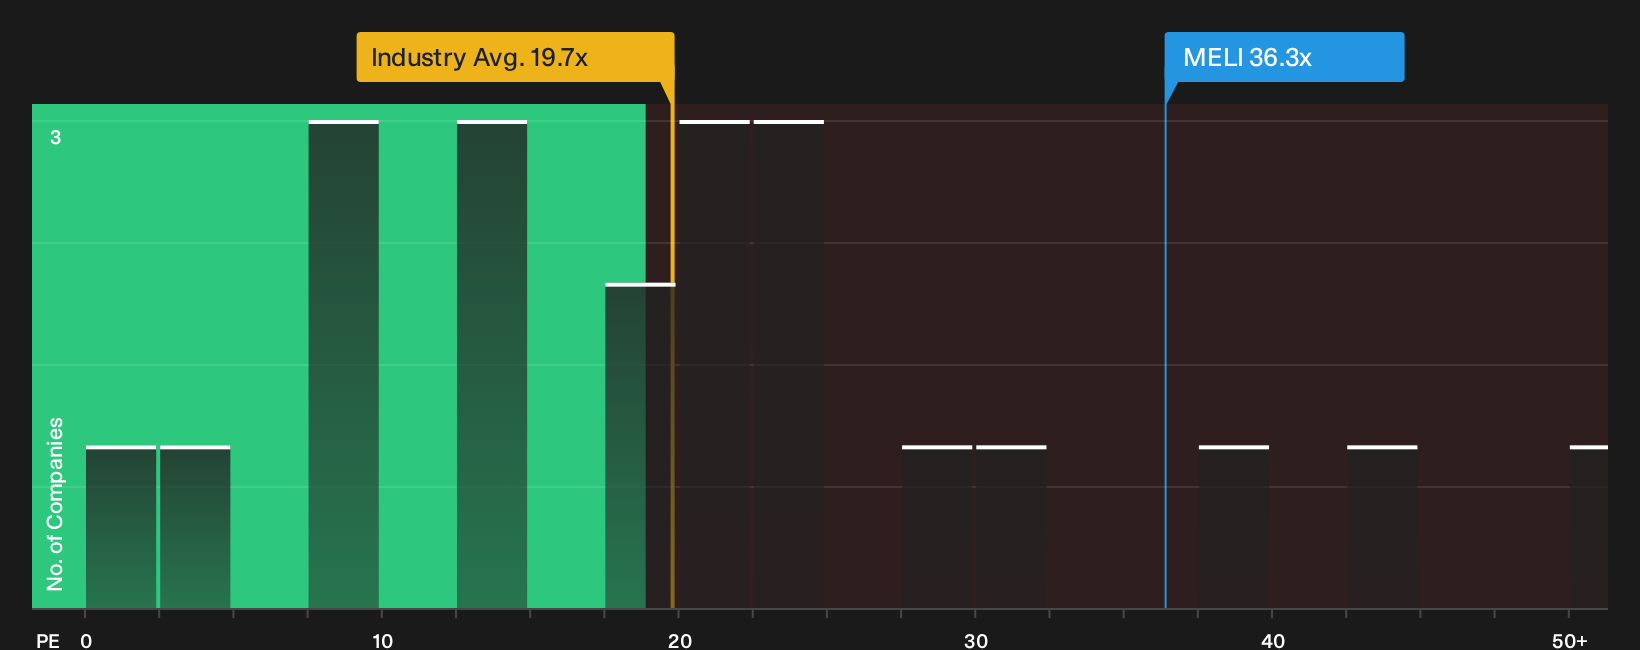
For a business like MercadoLibre that leans heavily on earnings power, the P/E ratio gives a clean read on how the market is pricing those profits. The stock trades on a P/E of 36.3x, which is roughly double the wider multiline retail industry on 18.7x and also ahead of the 17.1x peer group average. That indicates investors are paying a clear premium for MercadoLibre compared with more traditional retailers and similar companies in its space.
The Fair Ratio model, which aims to estimate the P/E you might expect given MercadoLibre's growth profile, margins, scale and risk, points to a level slightly below the current 36.3x. That places the shares a little above what this framework would treat as balanced rather than in obviously stretched territory, so any decision now comes down to how confident you are that the company can continue to justify a richer multiple than the sector. Explore the numbers behind MercadoLibre's P/E valuation.
The MercadoLibre Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where MercadoLibre's valuation question leaves off by spelling out which assumptions on growth, profitability and earnings power would need to hold for the stock to be worth meaningfully more or less than today, and they sit on the platform's Community page. Each narrative links a specific fair value view to a clear story about MercadoLibre's possible catalysts and risks, so you can track over time which version of events appears to be taking shape.
One of the top community narratives on MercadoLibre: 43% undervalued
According to John_Eric, a Simply Wall St Community investor who wrote the Narrative, MercadoLibre’s reported cash flow tells only part of the valuation story.
"Building a loan book fast costs cash up front, you hand out money now, collect interest for years…"
Discover why this Narrative puts MercadoLibre at 43% undervalued.
The last open question on MercadoLibre that the valuation cannot answer
Price and earnings only tell part of the story for MercadoLibre, because the research checks behind this analysis have also flagged specific risk factors that deserve a closer look from you. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com